Commercial Real Estate Valuation & Risk Estimator
Enter your property details to determine its estimated market value using the Direct Capitalization Approach and analyze the potential return on equity.
Enter values and click Calculate to see results.
You have probably heard the old adage that repeats itself in every property seminar and brokerage meeting: "Location, location, location." It sounds like a mantra for a reason. But if you ask seasoned investors in London or New York what actually drives returns, they will tell you something slightly different. The true golden rule of commercial real estate isn't just about where a building sits on a map. It is about understanding the relationship between physical location and financial performance.
Here is the reality check: A prime location with terrible management yields poor results. A mediocre location with brilliant operational efficiency can outperform expectations. So, what is the one rule? It is this: Value is determined by the income potential relative to risk, not just geography.
Rethinking the "Location" Myth
Why does everyone obsess over location? Because it is the only thing you cannot change. You can renovate a lobby, upgrade HVAC systems, or rebrand a retail center. You cannot move a building from Shoreditch to Mayfair overnight. This immutability makes location the primary driver of long-term stability. However, treating location as a standalone metric is a rookie mistake.
Think about it this way. Two office buildings might sit on the same street. One has triple-net leases with creditworthy tenants paying £40 per square foot. The other has short-term leases with struggling startups paying £35 per square foot and requires constant capital expenditure. Which one is the better investment? The first one, obviously. The location is identical, but the asset class differs because of the cash flow structure.
This brings us to the core concept of Net Operating Income (NOI). In commercial real estate, NOI is the lifeblood of valuation. It represents the revenue generated after operating expenses are deducted, but before debt service and taxes. If you ignore NOI in favor of flashy architectural features, you are buying a building, not an investment.
The Cap Rate Connection
To understand how location and value interact, you need to grasp the Capitalization Rate, or Cap Rate. This is the ratio of NOI to current market value, expressed as a percentage. It tells you what return you would get if you bought the property outright with no financing.
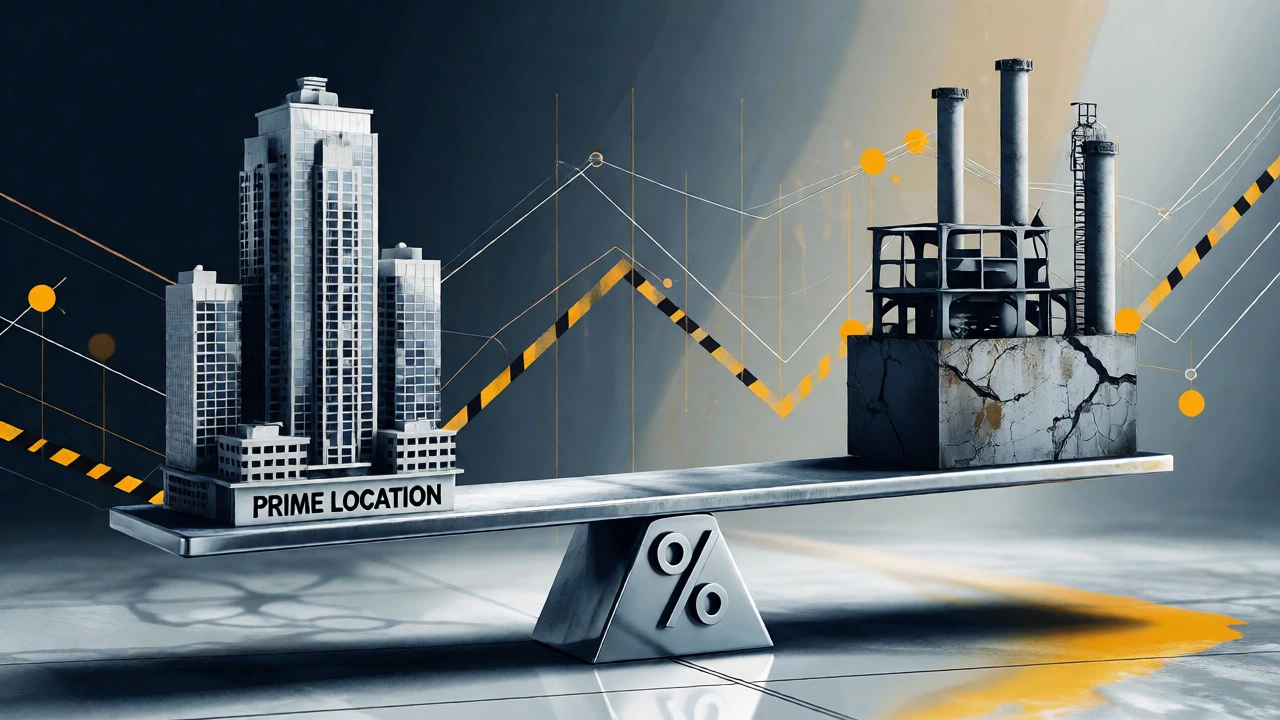
High-demand locations typically command lower cap rates. Why? Because the perceived risk is lower. Investors accept a smaller percentage return in exchange for the safety of a prime area. Conversely, secondary markets or areas with higher vacancy risks offer higher cap rates to compensate for that uncertainty.
Let’s look at a practical example. Imagine a retail unit in Central London. It might trade at a 4% cap rate. That means if the property generates £100,000 in annual NOI, its value is roughly £2.5 million. Now, look at a similar-sized industrial warehouse in an emerging logistics hub outside Birmingham. It might trade at a 6.5% cap rate. To generate the same £100,000 NOI, the value would be around £1.5 million. The industrial unit offers a higher yield, but carries more tenant turnover risk and potentially less capital appreciation than the London retail spot.
The rule here is simple: Match your cap rate expectations to your risk tolerance. Do not chase high yields without understanding why they exist. Often, a high cap rate signals a problem-like a bad lease structure or a deteriorating neighborhood-not a bargain.
Lease Terms Matter More Than Bricks
If location is the stage, the lease is the script. In residential real estate, leases are standard and short. In commercial property, they are complex legal documents that dictate cash flow for years, sometimes decades. The length of the lease, the type of tenant, and the escalation clauses determine whether your investment grows or stagnates.
Consider a Triple-Net Lease (NNN). In this arrangement, the tenant pays for property taxes, insurance, and maintenance. For the landlord, this is ideal. It provides predictable net income with minimal hassle. A NNN lease with a national brand like Starbucks or a major bank adds immense value to a property, regardless of minor location flaws.
On the flip side, gross leases put more burden on the landlord. If you buy a building with gross leases, you must budget for rising utility costs and repair bills. These expenses eat into your NOI, lowering your effective return. Therefore, when evaluating a deal, scrutinize the lease abstracts before you fall in love with the facade.
Due Diligence Is Non-Negotiable
Many new investors skip detailed due diligence because they fear losing the deal to another buyer. This is dangerous. Commercial real estate transactions involve significant sums, and errors are costly. You need to verify three critical areas:
- Physical Condition: Hire a professional surveyor. Look for roof integrity, foundation issues, and outdated mechanical systems. Replacing an HVAC system can cost tens of thousands of pounds.
- Financial Health: Audit the rent roll. Are tenants actually paying? What is the delinquency rate? Verify that the reported NOI matches bank statements.
- Legal Status: Check zoning laws. Can you use the space for your intended purpose? Are there pending litigation issues or environmental hazards?
A common pitfall is assuming that vacant space will fill up quickly. In a soft market, vacancy periods extend, and rental rates drop. Always stress-test your pro forma assumptions. What happens if occupancy drops to 80%? Does the deal still work?
Financing Leverage: The Double-Edged Sword
Most commercial deals rely on debt. Leverage amplifies returns. If you put down 25% and the property appreciates by 10%, your equity increases by 40%. That is powerful. But leverage also amplifies losses. If the property value drops by 10%, your equity shrinks by 40%.
Banks look closely at two metrics when approving loans: Loan-to-Value (LTV) and Debt Service Coverage Ratio (DSCR). LTV measures how much you owe compared to the appraised value. DSCR measures your ability to repay the loan from operating income. Most lenders require a DSCR of at least 1.25. This means your NOI must exceed your debt payments by 25%.
If interest rates rise, your debt service increases, potentially pushing your DSCR below the lender’s threshold. This triggers covenants that might force you to inject more cash or refinance under unfavorable terms. Always build a buffer into your financial model. Assume interest rates could rise by 1-2% and see if your deal survives.
Exit Strategy Planning
Every purchase should start with the end in mind. How will you sell? Who is the next buyer? Different strategies require different approaches.
| Strategy | Risk Level | Target Return | Time Horizon | Key Focus |
|---|---|---|---|---|
| Core | Low | 4-6% | Long (7+ years) | Stable cash flow, prime locations |
| Core Plus | Moderate | 6-9% | Medium (3-5 years) | Minor renovations, slight value-add |
| Value-Add | High | 10-15% | Short-Medium (2-4 years) | Major renovations, leasing up vacancies |
| Opportunistic | Very High | 15%+ | Variable | Development, land banking, distressed assets |
Core investments suit conservative investors seeking steady income. They often hold properties for a decade. Value-add strategies appeal to those willing to manage active projects. They buy underperforming assets, improve them, and sell at a higher valuation. Your personal appetite for risk and involvement dictates which category fits you best.
Market Cycles and Timing
Real estate moves in cycles. There are periods of expansion, peak, contraction, and trough. Trying to time the market perfectly is nearly impossible. Instead, focus on fundamentals. During economic downturns, prices may drop, offering entry points for patient buyers. During booms, competition heats up, compressing cap rates.
Keep an eye on supply pipelines. If hundreds of new office towers are breaking ground in your target city, expect increased competition for tenants in three years. Oversupply leads to falling rents and rising vacancy rates. Analyze local construction permits and planning applications to gauge future supply.
Demand drivers vary by sector. E-commerce growth boosts industrial demand. Remote work trends impact office spaces. Healthcare needs drive medical office development. Align your investment with macroeconomic trends rather than guessing based on gut feeling.
Practical Checklist for Buyers
Before signing any contract, run through this checklist. It helps avoid emotional decisions and keeps you grounded in data.
- Analyze the Rent Roll: List every tenant, their lease expiration date, and current rent. Identify rollover clusters where multiple leases expire simultaneously.
- Review Operating Expenses: Compare historical opex against industry benchmarks. Are utilities unusually high? Is there hidden deferred maintenance?
- Inspect the Physical Asset: Walk the property yourself. Smell for mold. Listen for noisy machinery. Talk to existing tenants if possible.
- Verify Title and Zoning: Ensure there are no easements or restrictions that limit future use.
- Model Sensitivity Scenarios: Calculate returns if vacancy rises by 5% or if interest rates jump by 1%.
Remember, the goal is not to find the perfect building. It is to find a mispriced asset where you can create value through better management, renovation, or repositioning.
Is location really the most important factor in commercial real estate?
While location is critical because it cannot be changed, it is not the sole determinant of success. Financial performance, driven by Net Operating Income (NOI) and lease structures, often outweighs pure geography. A well-managed property in a secondary location can outperform a poorly managed one in a prime area.
What is a good cap rate for commercial property?
There is no universal "good" cap rate. It depends on the asset class, location, and risk profile. Prime office spaces in major cities like London might have cap rates of 4-5%, while industrial warehouses in secondary markets might offer 6-8%. Higher cap rates generally indicate higher risk.
How do I calculate the value of a commercial property?
The most common method is the Direct Capitalization Approach. You divide the Net Operating Income (NOI) by the Capitalization Rate (Cap Rate). Formula: Value = NOI / Cap Rate. For example, if NOI is £100,000 and the Cap Rate is 5% (0.05), the value is £2,000,000.
What are the biggest risks in commercial real estate investing?
Key risks include tenant default, rising interest rates affecting refinancing, unexpected capital expenditures (like roof replacements), and market downturns leading to decreased valuations. Proper due diligence and conservative financial modeling help mitigate these risks.
Do I need a large deposit to buy commercial property?
Typically, lenders require a down payment of 20-30% of the purchase price. Some specialized loans may allow lower equity, but this comes with stricter covenants and higher interest rates. Having reserves for closing costs and immediate repairs is also essential.